
Veteran-owned and operated
Chicagoland VA Loan Real Estate Agents from a Veteran-Owned Brokerage
Dorazio Real Estate is a veteran-owned and operated Chicago brokerage. We help veterans, active-duty service members, and military families use the VA loan to buy, sell, and invest across Chicago and the suburbs.
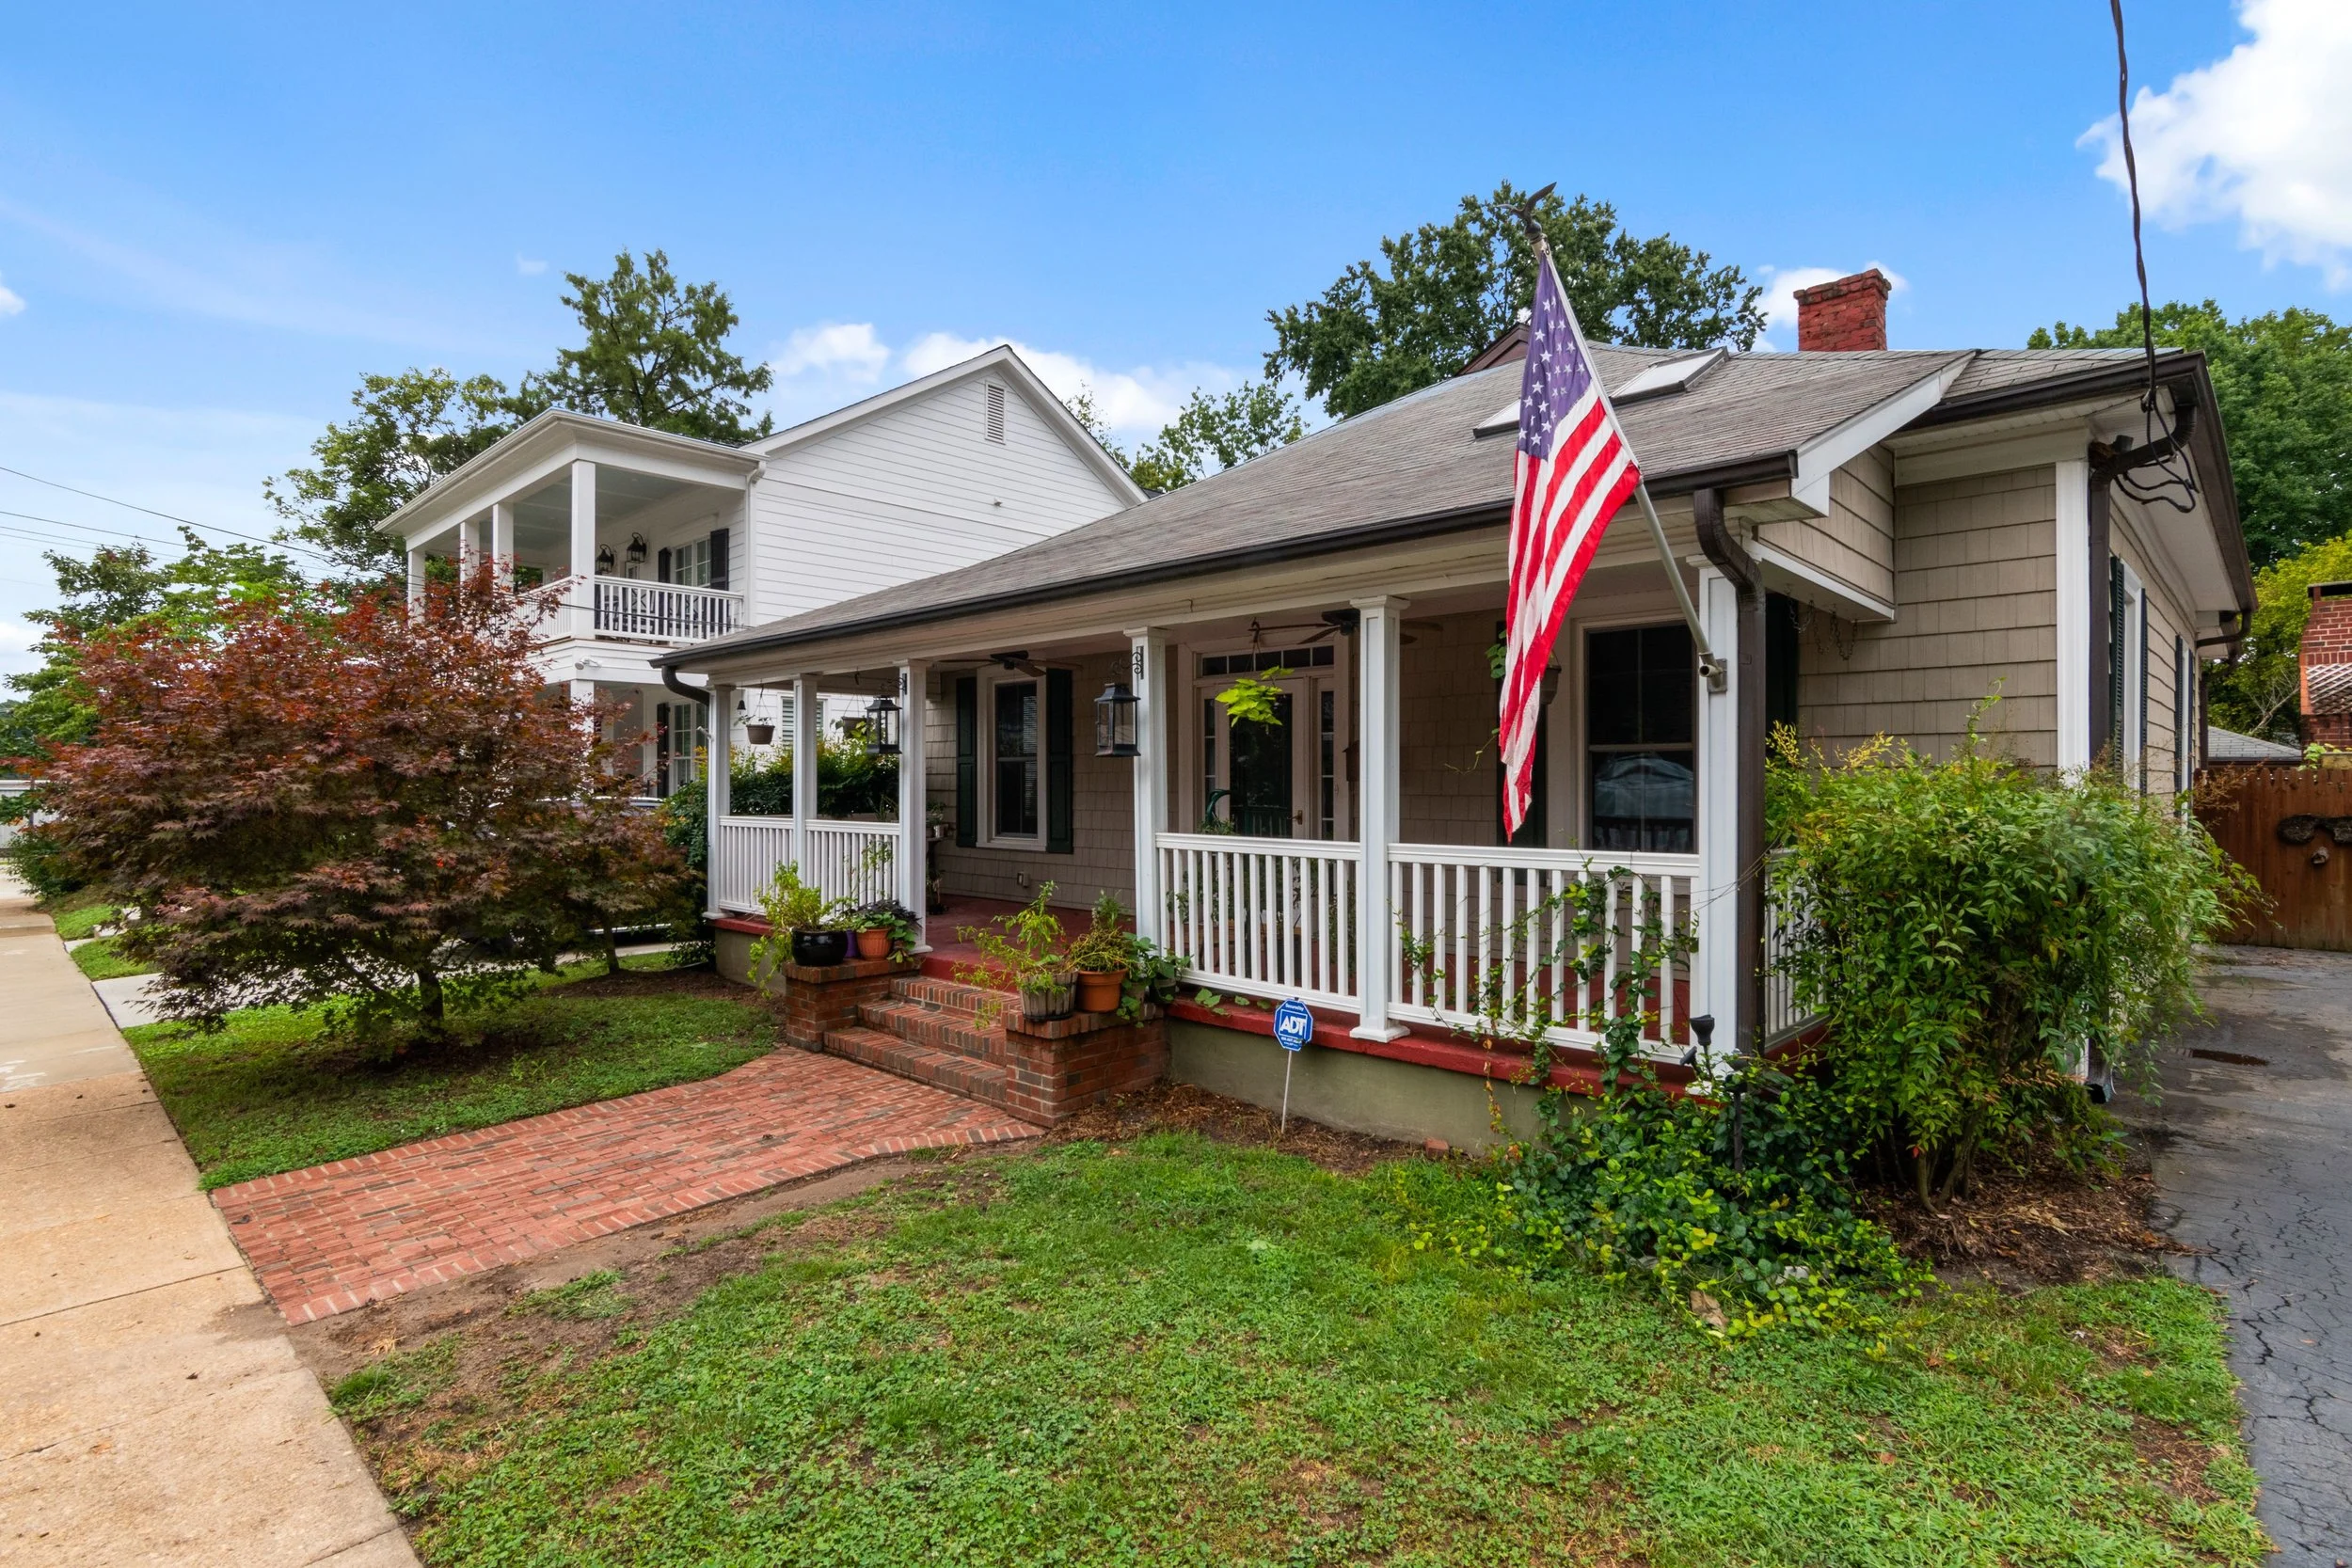
Photo: Curtis Adams, Pexels.
Why veterans call us
A veteran-owned and operated brokerage
Our managing broker is a former U.S. Army officer and a West Point graduate. We put a special emphasis on helping veterans and active military reach their real estate goals, and the VA loan is a big part of that work.
Led by an Army veteran
Dorazio Real Estate is veteran-owned and operated. We've bought and sold homes and investment property across Chicagoland for more than 15 years.
An agent who has used the benefit
One of our agents served in the U.S. Army Reserve and bought a three-unit building with a VA loan. That agent lived in one unit, let the rent from the other two help cover the mortgage, and now works with VA buyers who want to do the same.
Homes for Heroes affiliate
We're a Homes for Heroes affiliate. Veterans and active-duty service members who buy or sell with us get a Hero Rewards check after closing. You need to enroll before you start, so read how the rebate works first.
The VA loan benefit
What a VA loan gives a Chicago buyer
A VA-backed purchase loan lets you buy with no down payment, as long as the sale price doesn't top the appraised value. You'll need a Certificate of Eligibility, you'll need to meet the VA's and your lender's credit and income standards, and you have to live in the home.
No down payment
You can borrow up to the conforming loan limit with nothing down in most areas. If you want to borrow more, you can add a down payment.
No monthly mortgage insurance
VA loans carry no private mortgage insurance and no FHA mortgage insurance premium. Conventional lenders usually require PMI when you put down less than 20%.
A one-time funding fee, with exemptions
Most VA buyers pay a funding fee at closing or roll it into the loan. You don't pay it if you receive VA compensation for a service-connected disability. The VA also waives it for a few other groups, including surviving spouses who receive Dependency and Indemnity Compensation.
A benefit you can use again
Your benefit doesn't end with the first home. You can use it again after you sell or refinance a home bought with a VA loan, and in some cases you can buy a second home while you still own the first.
The VA's own rules are on VA.gov. Our blog goes deeper on how entitlement works, the funding fee exemption for disabled veterans, and what the benefit gives a military spouse.
House hacking
Buy a 2-4 flat with a VA loan
A VA loan can buy a building with up to four units, as long as you live in one of them. Rent from the other units can help carry the mortgage.
Your lender will look at the projected rent, your cash reserves, and the building's condition before approving a multi-unit purchase. Bring us in early. We help you compare the rent with similar units nearby, check the permits and zoning for each unit, and test whether the numbers hold up through a vacancy or a big repair.
Our managing broker owns multifamily buildings, and our sister company, BCG Real Estate Group, manages rental property in Chicago. Read the VA loan house hack for the full walkthrough, or using a VA loan on a home with an ADU if a coach house is in the picture. For a building you're serious about, our multifamily investment analysis covers the rent roll, operating expenses, cash flow, and financing scenarios.
Before you write the offer
Condos, condition, and the VA appraisal
A VA loan can buy a condo only in a building the VA has approved. Check the building before you fall for the unit. If it isn't approved, the VA loan is off the table for that address.
The VA appraisal looks at the home itself as well as the price. Roof condition, safety items, peeling paint, mechanical systems, and deferred maintenance can all come up. We walk through those items with you on the tour, while you still have room to shape the offer or move on.
One of our agents is an IBEW electrician and brings a trained eye for a home's systems and safety to every showing.
After you close
Illinois property tax relief for disabled veterans
Illinois lowers the taxable value of your primary residence if the VA has rated you 30% or more for a service-connected disability. The state calls it the Standard Homestead Exemption for Veterans with Disabilities.
30% to 49% rating
The exemption takes $2,500 off your home's equalized assessed value.
50% to 69% rating
The exemption takes $5,000 off your home's equalized assessed value.
70% rating or higher
The first $250,000 of equalized assessed value is exempt. The Cook County Assessor's Office says that is likely to erase the property tax on the home.
In Cook County you apply with the Assessor's Office. In DuPage, Lake, Will, and Kane counties you file Form PTAX-342 with the county's chief assessment office. Most veterans reapply each year.
The exemption belongs to the owner. If the seller of a home you like is a disabled veteran, the listing's tax bill can look far lower than the one you'll get. We estimate the bill without the seller's exemptions before you set your budget. Our post on the exemption in Cook County covers the paperwork, surviving spouses, and how to claim missed years.
Moving in or out
PCS orders and moves
PCS orders set your calendar before you've seen a single house. If you're moving to Chicagoland, our relocation concierge helps you compare neighborhoods, commutes, schools, and housing options from a distance. If you're leaving Illinois, we connect you with a military-aligned agent at your next station through the MIL-Estate network.
Already own a VA-financed home and got new orders? You can keep it, rent it, or sell it. Read what happens to your VA loan when you PCS and how BAH affects what you can afford before you decide.
Local guides
VA loan help by town
Each town guide has a section for veterans with what to check before you buy there with a VA loan.
- VA loan help in Beverly and Mt. Greenwood
- VA loan help in Oak Lawn
- VA loan help in Evergreen Park
- VA loan help in Palos Hills, Palos Park, and Palos Heights
- VA loan help in Alsip
- VA loan help in Bridgeview
- VA loan help in Hickory Hills
- VA loan help in Willow Springs
- VA loan help in Blue Island
- VA loan help in Wheaton
- VA loan help in Naperville
- Every area we serve
Questions veterans ask
VA loan questions from Chicago buyers
Do I need a down payment to buy in Chicago with a VA loan?
No, in most cases. A VA-backed purchase loan needs no down payment as long as the sale price isn't higher than the appraised value and the loan stays within the conforming limit. You'll still have closing costs, and the seller can pay some of them.
Can I buy a two-flat or three-flat with a VA loan?
Yes. A VA loan can buy a building with up to four units, as long as you live in one of them. Your lender will review the projected rent, your reserves, and the building's condition, so compare the rent with the taxes, insurance, and repairs before you write the offer.
Can I use a VA loan on a Chicago condo?
Yes, if the VA has approved the condo building. Check the approval before you write an offer. Then review the association's dues, reserves, special assessments, and rules on pets and rentals.
Do disabled veterans pay the VA funding fee?
No. If you receive VA compensation for a service-connected disability, the VA waives the funding fee. If the VA later awards you compensation with an effective date before your closing, you may qualify for a refund.
How much does the Illinois disabled veteran exemption save?
It depends on your rating. A rating of 30% to 49% takes $2,500 off your home's equalized assessed value, 50% to 69% takes $5,000 off, and 70% or higher exempts the first $250,000. Multiply the reduction by the tax rate on your bill to see your savings.
Can I use my VA loan benefit more than once?
Yes. You can use it again after you sell or refinance a home you bought with a VA loan. Some buyers can also purchase a second home with remaining entitlement while they still own the first, which can help after a PCS move.
What should I do before I start touring homes?
Request your Certificate of Eligibility, get preapproved with a lender who knows VA loans, and enroll in Homes for Heroes if you want the rebate. If you've already signed with another agent, the rebate is off the table, so call us first and we'll handle the enrollment.
Start with a conversation
Talk to a veteran-owned team before you tour
Tell us where you're stationed or where you want to live, and what you want the home to do for you. We'll talk through the VA loan, the towns that fit, and what to check before you make an offer.
Bring your orders, the listing, or the question.
Or send a note through our contact page.