What Happens to Your VA Loan When You PCS?
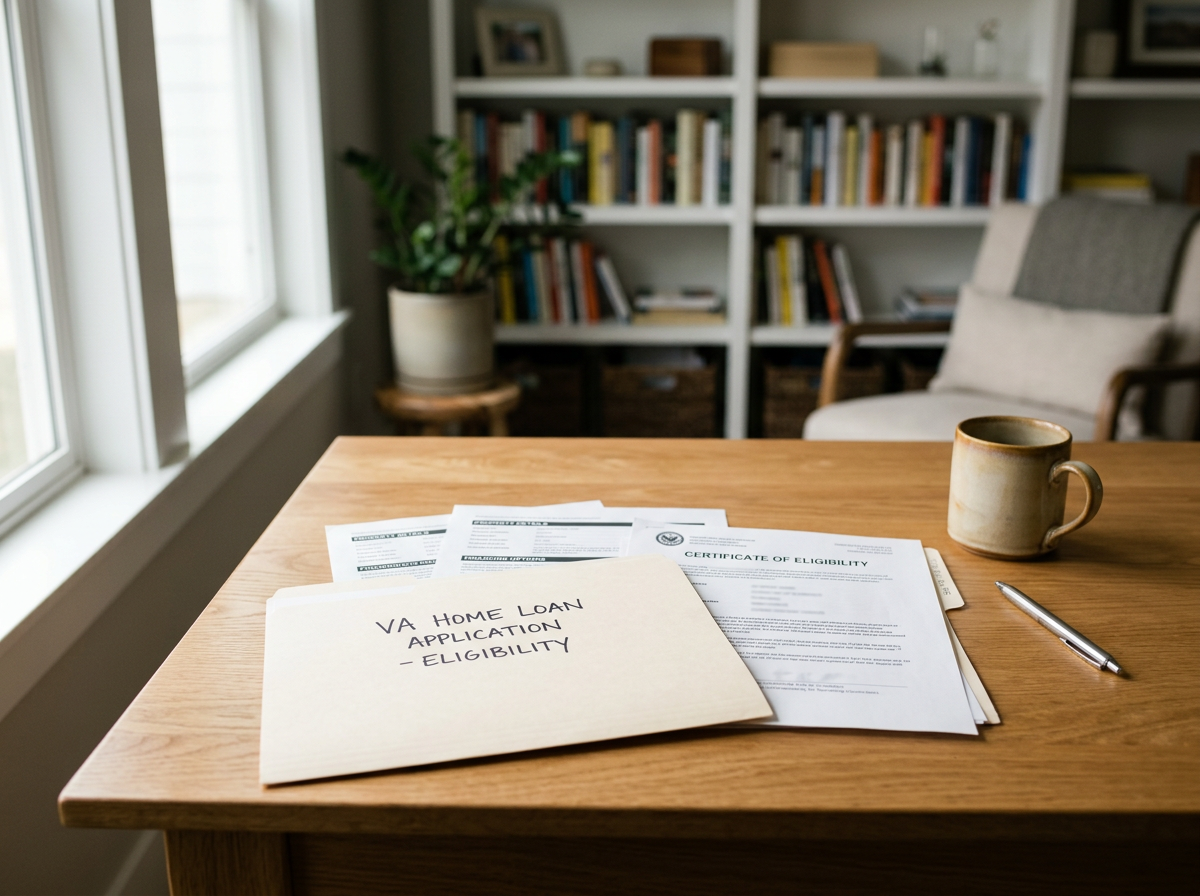
PCS orders do not cancel your VA loan or force you to sell the home. The mortgage stays in place after you move, and you can keep the property as a rental if you satisfied the occupancy requirements tied to the original purchase. You may also have enough remaining VA entitlement to finance a primary home near the next duty station, though that calculation can require a down payment.
Before you list the home or sign a lease, ask a VA-experienced lender to review your Certificate of Eligibility and current payment. The lender can tell you whether the existing loan leaves enough entitlement and room in your budget for another purchase. Need a recommendation? Just ask!
Your Existing VA Loan Remains in Place
The VA loan stays attached to the property when you transfer. Its balance, rate, and payment terms remain the same unless you sell, refinance, or arrange an approved assumption. You remain responsible for the debt while your name stays on it.
VA occupancy rules focus on your intent at purchase. VA guidance defines 60 days after closing as a reasonable time for occupancy, with exceptions for some delays. The VA lender handbook includes an example of a service member who transfers overseas and rents the former home.
Talk with the servicer before converting the property to a rental. You will also need landlord insurance, any association approval, and compliance with local rental rules. A Chicago condo and a single-family home near Naval Station Great Lakes can have different requirements.
Keeping the Home Requires More Than Matching Rent to the Mortgage
A rental can make sense if you expect to return or have a favorable rate. Start with market rent, then subtract vacancy, management, repairs, insurance, association charges, property taxes, and a reserve for large replacements.
Chicagoland property taxes and older homes deserve attention. A two-flat with aging mechanical systems can collect good rent and still demand a large reserve. A condo may need less exterior maintenance, but its association could restrict leasing or impose move fees.
Someone must respond when the heat stops in January, approve repairs, inspect between tenants, and cover the payment during a vacancy. Base the decision on a year that includes an empty month or an expensive repair.
Remaining Entitlement May Support Another Purchase
You may qualify for another VA loan if you have enough remaining entitlement and meet the lender's underwriting and occupancy requirements. The VA calculates remaining entitlement from 25 percent of the applicable county loan limit, minus entitlement already used and not restored.
VA applies the county loan limit for the location of the next property. If the available guaranty does not cover the amount your lender requires, you may need a down payment.
Request an updated Certificate of Eligibility before setting a purchase budget. The COE shows entitlement charged to prior VA loans. Your lender can compare it with the county limit and proposed loan.
You must use the new property as your primary residence. You cannot use remaining entitlement to finance another investment purchase.
A Lease Does Not Remove the Old Payment From Underwriting
A tenant's rent can help with the old mortgage, but your next lender decides how to treat it. VA guidance permits consideration of prospective rent from a departing residence. The lender may request a lease, review the rental market, and require cash reserves.
The lender may use projected rent to offset the old payment instead of adding it to qualifying income. Get that review before touring homes so you know how the lender will count rent and how much cash must remain after closing.
Selling Clears the Loan and Can Restore Entitlement
Selling may suit a family that wants its equity or does not want to manage from another state. After you sell the home and pay the loan in full, you can request restoration of the entitlement used for that purchase.
Ask the lender to obtain an updated COE or submit a restoration request through VA.gov. If a buyer assumes your loan without substituting eligible entitlement, part of yours may remain tied to it. Have the servicer explain the effect before accepting an assumption offer.
BAH Follows the New Assignment, Not the Old Mortgage
The Department of Defense bases Basic Allowance for Housing on duty location, pay grade, and dependency status when the installation does not provide government housing. A rental at the prior station does not set the new BAH rate.
BAH does not guarantee that rent will cover the old home's expenses. Compare the new housing payment, the rental's possible shortfall, moving costs, and cash reserves before committing to two properties.
Common PCS Questions About VA Loans
Do I have to sell after receiving PCS orders? No. You may sell or keep the home, and the VA loan can remain while you rent it.
Can I use another VA loan? You may qualify with enough remaining entitlement and lender approval. Your lender must calculate the guaranty for the county where you plan to buy.
Does renting violate VA occupancy rules? Renting after a good-faith purchase and occupancy differs from using a VA purchase loan for an investment property. Ask the lender about any original occupancy delay or exception.
Who should review the plan first? A VA-experienced lender can retrieve your COE and calculate entitlement. A local real estate professional can estimate sale price, rent, and ownership costs.
We are veteran-led and a Mil-Estate affiliate. We help military families moving into Chicagoland evaluate property and market details, and we connect families leaving the area with referral partners near their next duty station. If you are weighing a sale against a rental, we are available to work through the real estate side with you.