
Mixed-use property
Chicago Mixed-Use Property Sales and Leasing
Dorazio Real Estate lists and buys mixed-use retail and residential buildings across Chicagoland, from a storefront with apartments upstairs to larger buildings. Our sister company manages mixed-use buildings too, so we read both sides of the rent roll before we talk price.
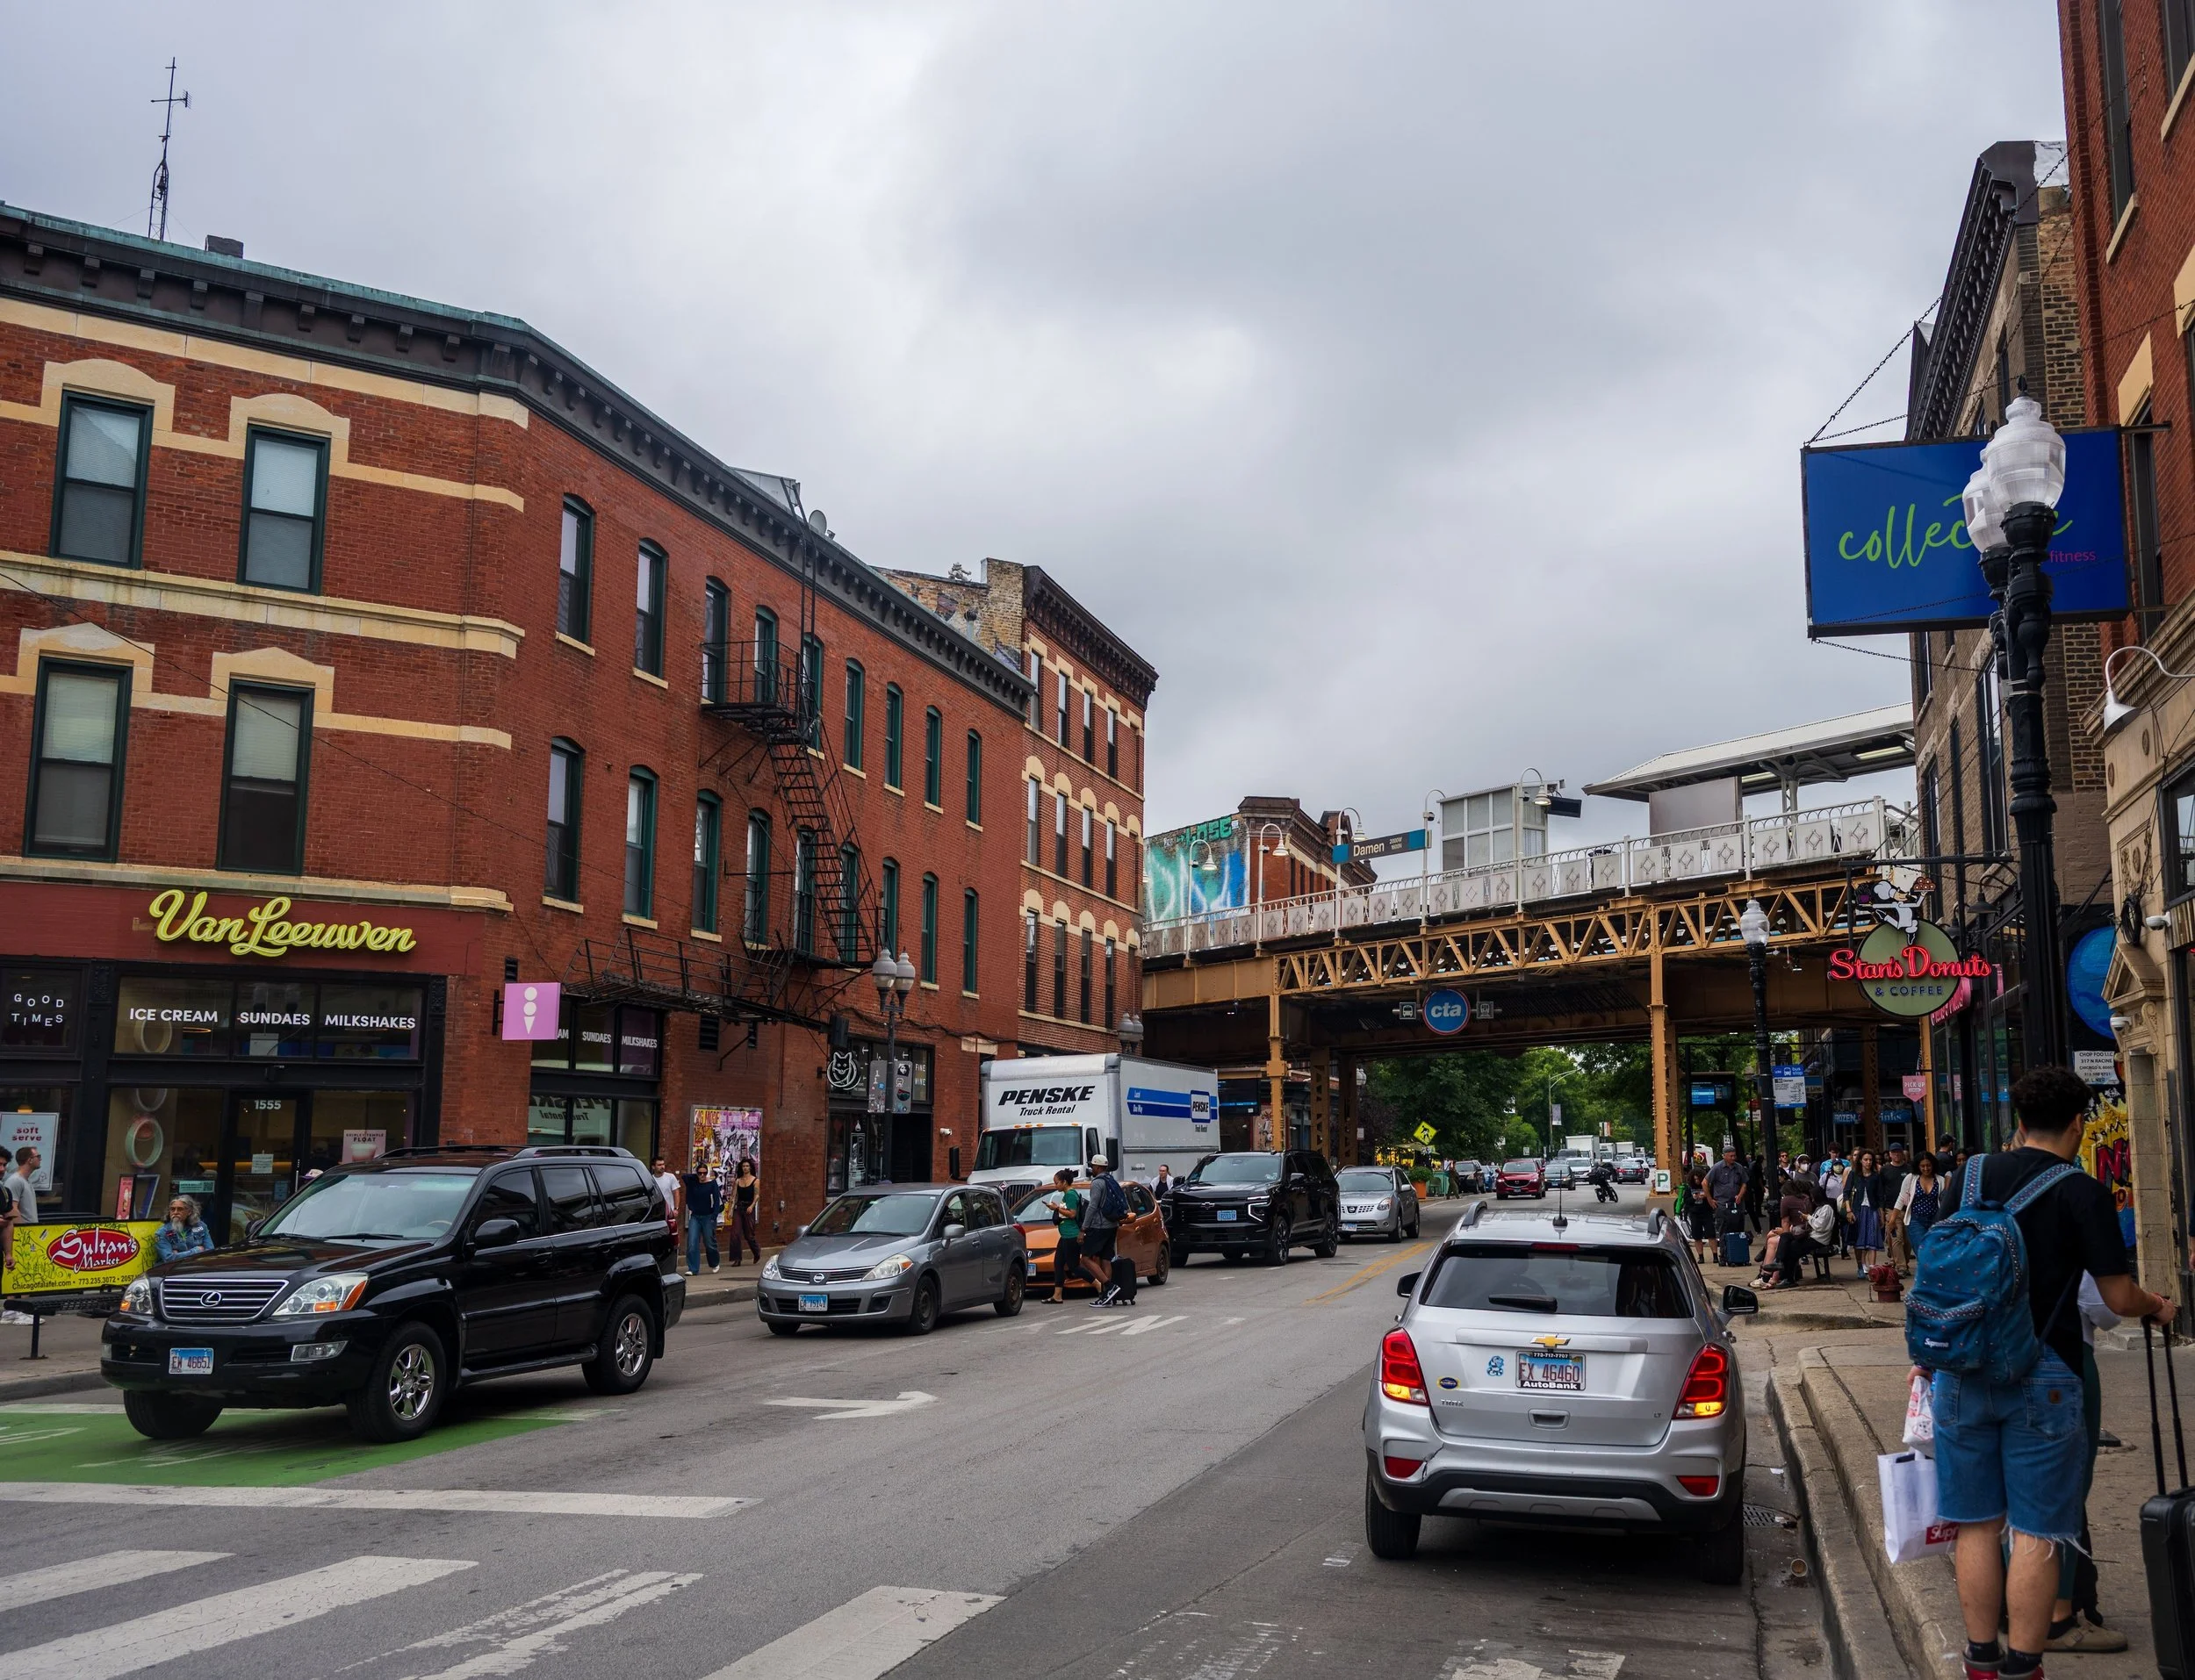
Photo: Guohua Song, Pexels.
What we work on
Two kinds of tenants in one building
A mixed-use building combines apartments with commercial space such as a shop or an office. Each side brings its own tenants, leases, and risks, and you have to underwrite both before you buy.
Storefront with apartments upstairs
This building has a shop on the ground floor and one or more apartments above it. With four units or fewer, you may be able to live upstairs and buy with an FHA loan.
Larger retail and residential buildings
Buildings with several storefronts or more apartments trade on their income. Buyers compare the rent roll, the expenses, and the condition against similar buildings nearby.
Before the offer
What we check before you buy
Both rent rolls
Commercial and residential tenants sign different leases with different terms. We compare each lease with the rent roll, and we ask for 24 to 36 months of income and expense records up front, since a buyer's lender will want to verify them.
Zoning and legal use
Confirm that the zoning allows each current use and the number of apartments. Our brokerage has dealt with a zoning certification issue that surfaced at the last minute of an otherwise smooth closing. We check zoning before you write the offer.
Taxes and expenses
Cook County taxes can change the monthly math in a hurry. We pull the tax history and look at insurance, utilities, and maintenance for each side of the building.
Cap rate against interest rates
Know the local cap rate and how it compares with today's loan rates. If a building's cap rate sits below your interest rate, your loan costs more than the building earns on its price.
Loans and limits
Financing a mixed-use building
FHA insures mixed-use buildings of one to four units when at least 51 percent of the building's square footage is residential and the commercial use doesn't affect the health and safety of the people who live there. You also have to live in the building.
A VA loan also requires you to live in the property. Ask a VA lender how it treats the storefront before you count on one.
Buildings with five or more apartments fall outside VA and FHA home loans, and so does any building you won't live in. Those need commercial or investor financing, so talk to a lender before you make an offer.
For owners
Selling a mixed-use building
Buyers of mixed-use buildings buy the income. Gather leases, rent rolls, expense records, tax bills, and repair invoices for both sides before the listing goes live, so buyers can underwrite the building fast.
A measured floor plan shows the storefront and each apartment to buyers who can't tour occupied units. For a value without listing, order a broker price opinion. Our listing agents page covers how we price and market a property.
After you buy
Leasing and management
We handle sales and leasing for mixed-use buildings. After you buy, our sister company, BCG Real Estate Group, can manage the building. BCG coordinates the commercial and residential tenants and handles each lease structure. See our property management page.
Thinking of furnishing the apartments for monthly guests? See short-term rental investing. Buying a building that needs a full rehab? See fix and flip, and our multifamily and investment property page for apartment-only buildings.
Questions buyers and owners ask
Mixed-use property questions
Can I buy a mixed-use building with an FHA loan?
Yes, if it has one to four units, you live there, at least 51 percent of the square footage is residential, and the commercial use doesn't affect the health and safety of the residents.
Can I use a VA loan on a mixed-use building?
Ask your lender before you write the offer. A VA loan requires you to live in the property, and the lender decides how it treats the commercial space.
What should I ask the seller for?
Rent rolls and leases for every commercial and residential tenant, plus 24 to 36 months of income and expense records, tax bills, and service records.
How do you value a mixed-use building?
By its income. We compare the building's net operating income with the local cap rate, then check the result against recent sales of similar buildings.
Who manages a mixed-use building after I buy it?
Our sister company, BCG Real Estate Group, manages commercial and mixed-use buildings in Chicago.
Start with a conversation
Bring us the building
Send the listing, the rent roll, or the address. We'll talk through both sides of the income, the zoning, and how you'd finance it.
Or send a note through our contact page.