Real Estate Tips for Military Families Buying in Illinois
Buying or selling a home is a lot to take in even under normal circumstances, and a PCS move, a deployment, or a tight military timeline adds a layer most buyers never have to deal with. As part of the Mil-Estate network, we work through this with military families constantly, and most of the confusion comes down to the same handful of things: knowing what's actually in the contract, and knowing how to manage the process when you can't just show up in person.
Read Everything, Even the Boring Parts
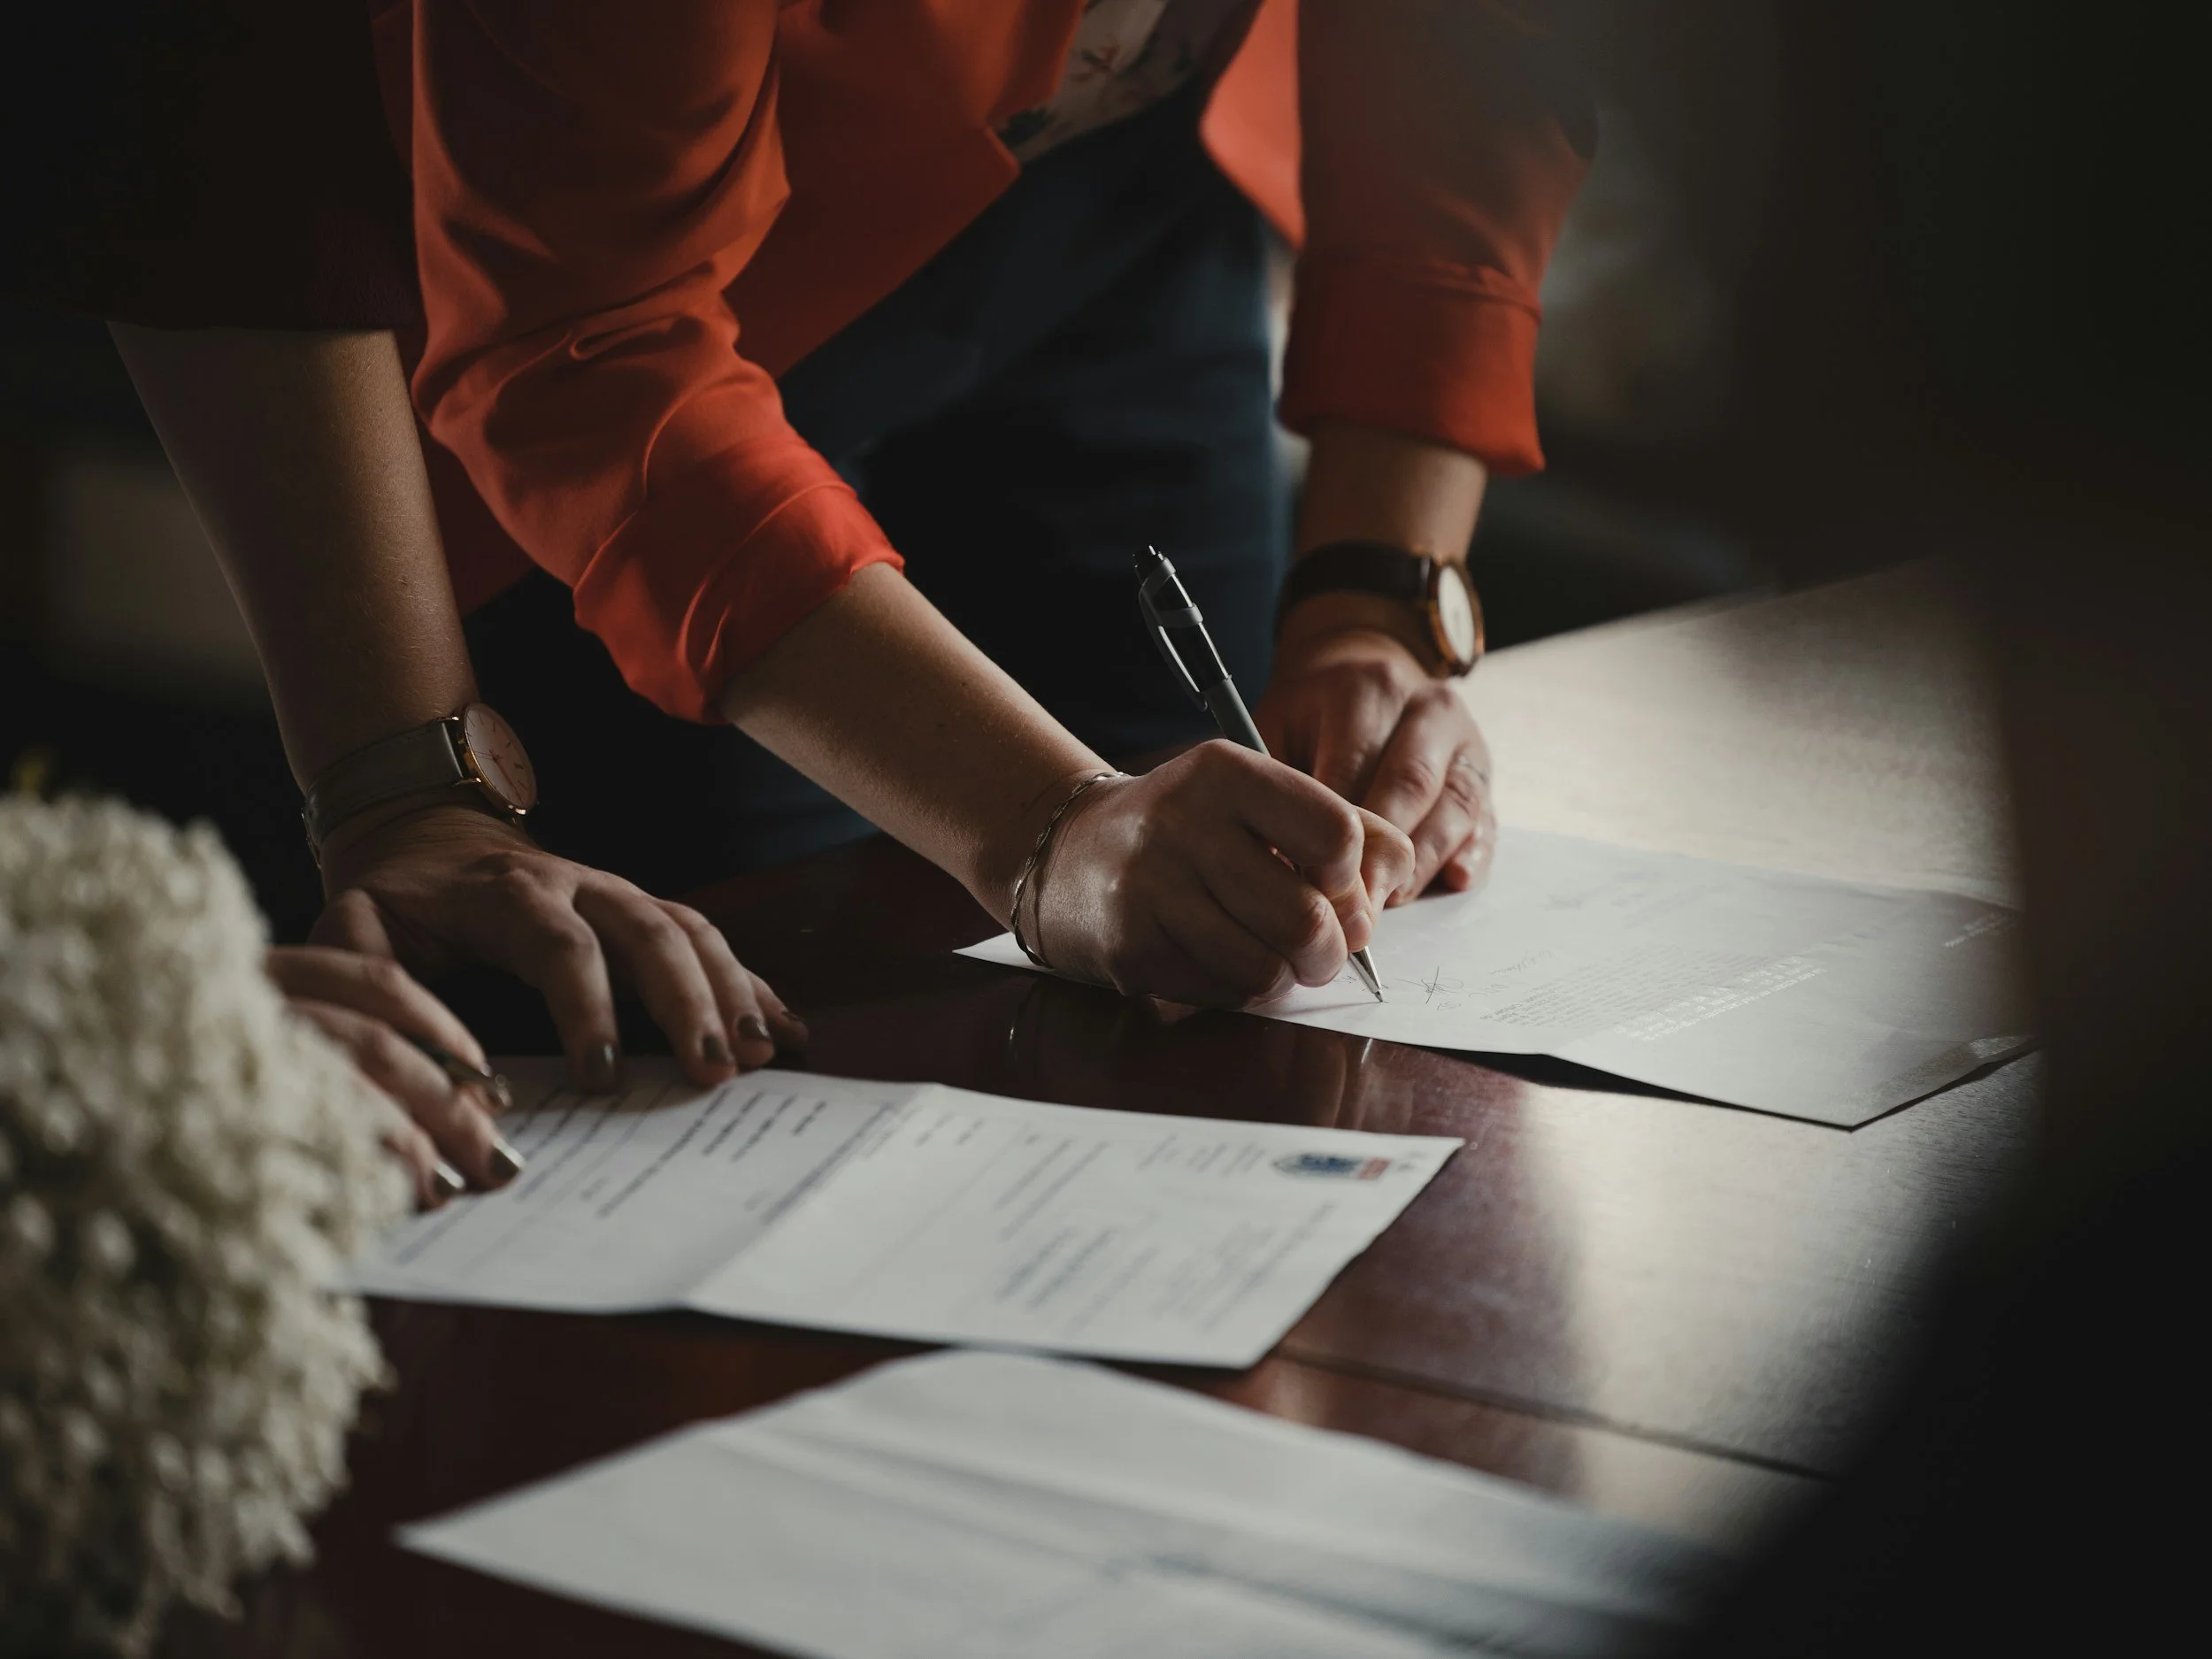
It's easy to skim a contract and sign where you're told to sign, but the details matter. Pay attention to the purchase price and financing terms, the contingencies that have to be met before the sale can close, the earnest money deposit you're putting down, and the closing date and deadlines that govern the whole timeline. Skipping past any of these is how buyers and sellers end up surprised later in the process.
The Terms Worth Knowing
A handful of terms show up in almost every contract, and knowing them going in makes the rest of the process easier to follow.
Earnest money is a deposit that shows you're serious about the purchase. It's usually applied toward closing costs, though it can be forfeited if you back out for reasons the contract doesn't cover.
A contingency is a condition, like financing approval, a clean inspection, or an appraisal coming in at value, that has to be met before the sale can close.
Closing costs are the fees beyond the purchase price itself: lender fees, title insurance, and escrow charges.
An appraisal is the lender's own estimate of the home's value, done to confirm it's worth what they're lending against it.
Escrow is the third-party account holding funds and documents until closing is final.
Ask Before You Assume
If a clause doesn't make sense, ask your agent or a real estate attorney before you sign, not after. Common questions worth asking up front: what happens if you need to back out, what you're on the hook for financially if the deal falls through, whether there are penalties for missing a deadline, and how the inspection contingency actually works. A good agent will walk you through this in plain language. For anything more complex, particularly if you're selling remotely during a relocation, an attorney familiar with military-specific requirements is worth the call.
Deadlines Don't Move for a PCS
Contracts run on strict deadlines: submitting your earnest money, completing inspections and requesting repairs, securing mortgage approval, and meeting the closing date itself. None of those move just because your orders did. If you know a PCS is coming, start your search and your paperwork earlier than you think you need to, so the transaction timeline doesn't collide with your move date.
Managing It All From a Distance
A lot of this process doesn't require you to be in the room anymore. Virtual tours, online document signing, and video calls with your agent make it possible to stay on top of a purchase or sale while you're on duty or deployed. Keep your contracts, inspection reports, and agent communication somewhere organized and easy to reach, since you won't always have time to dig for a document on short notice. And don't overlook the relocation assistance programs the military already offers. They exist to help with exactly this kind of logistics.
Work With Someone Who Knows the Territory
VA loan requirements, PCS logistics, remote closings: none of it is exotic to an agent who works with military families regularly, but it trips up a lot of first-time buyers who don't have that guidance. As part of the Mil-Estate network, this is what we do. If you're buying, selling, or just trying to figure out the timeline, reach out and we'll walk you through it.